Quick answer
A residual stock loan is a short-term private loan secured on completed but unsold dwellings from a development. It repays the construction lender when its facility expires, giving the developer time to sell the remaining units at a fair price instead of discounting. It is repaid as each unit settles, with interest that can be prepaid or capitalised so there may be no monthly repayments.
Key points
- Secured on finished, titled units or houses, not on a project under construction
- Clears an expiring construction facility so you aren't forced into a fire sale
- Repaid progressively as each unit settles
- Interest can be prepaid or capitalised, so cash flow isn't squeezed while you sell
- No formal valuation required, which keeps the refinance moving
- Amounts
- $20k – $5m
- Term
- 1 to 24 months
- Security
- Completed, titled stock
- Repayments
- Interest can be prepaid or capitalised
The build is finished, the occupation certificate is in hand and the titles have issued. Most of the project has sold. But a handful of units are still on the market, and the construction facility is about to hit its expiry date.
That is the classic residual stock problem. The asset is good, but the debt is on the wrong clock. A residual stock loan resets that clock.
What is a residual stock loan?
It is a private first mortgage (or occasionally a second mortgage) secured over completed, individually titled dwellings that a developer still owns after a project ends. The loan pays out the construction lender, and is then repaid unit by unit as the remaining stock sells.
Because the security is finished property rather than a building site, this isn’t construction finance. The lender is looking at real homes with real comparable sales, which is a far simpler assessment than a cost-to-complete model.
Typical residual stock scenarios include:
- the last few apartments in a mid-rise block
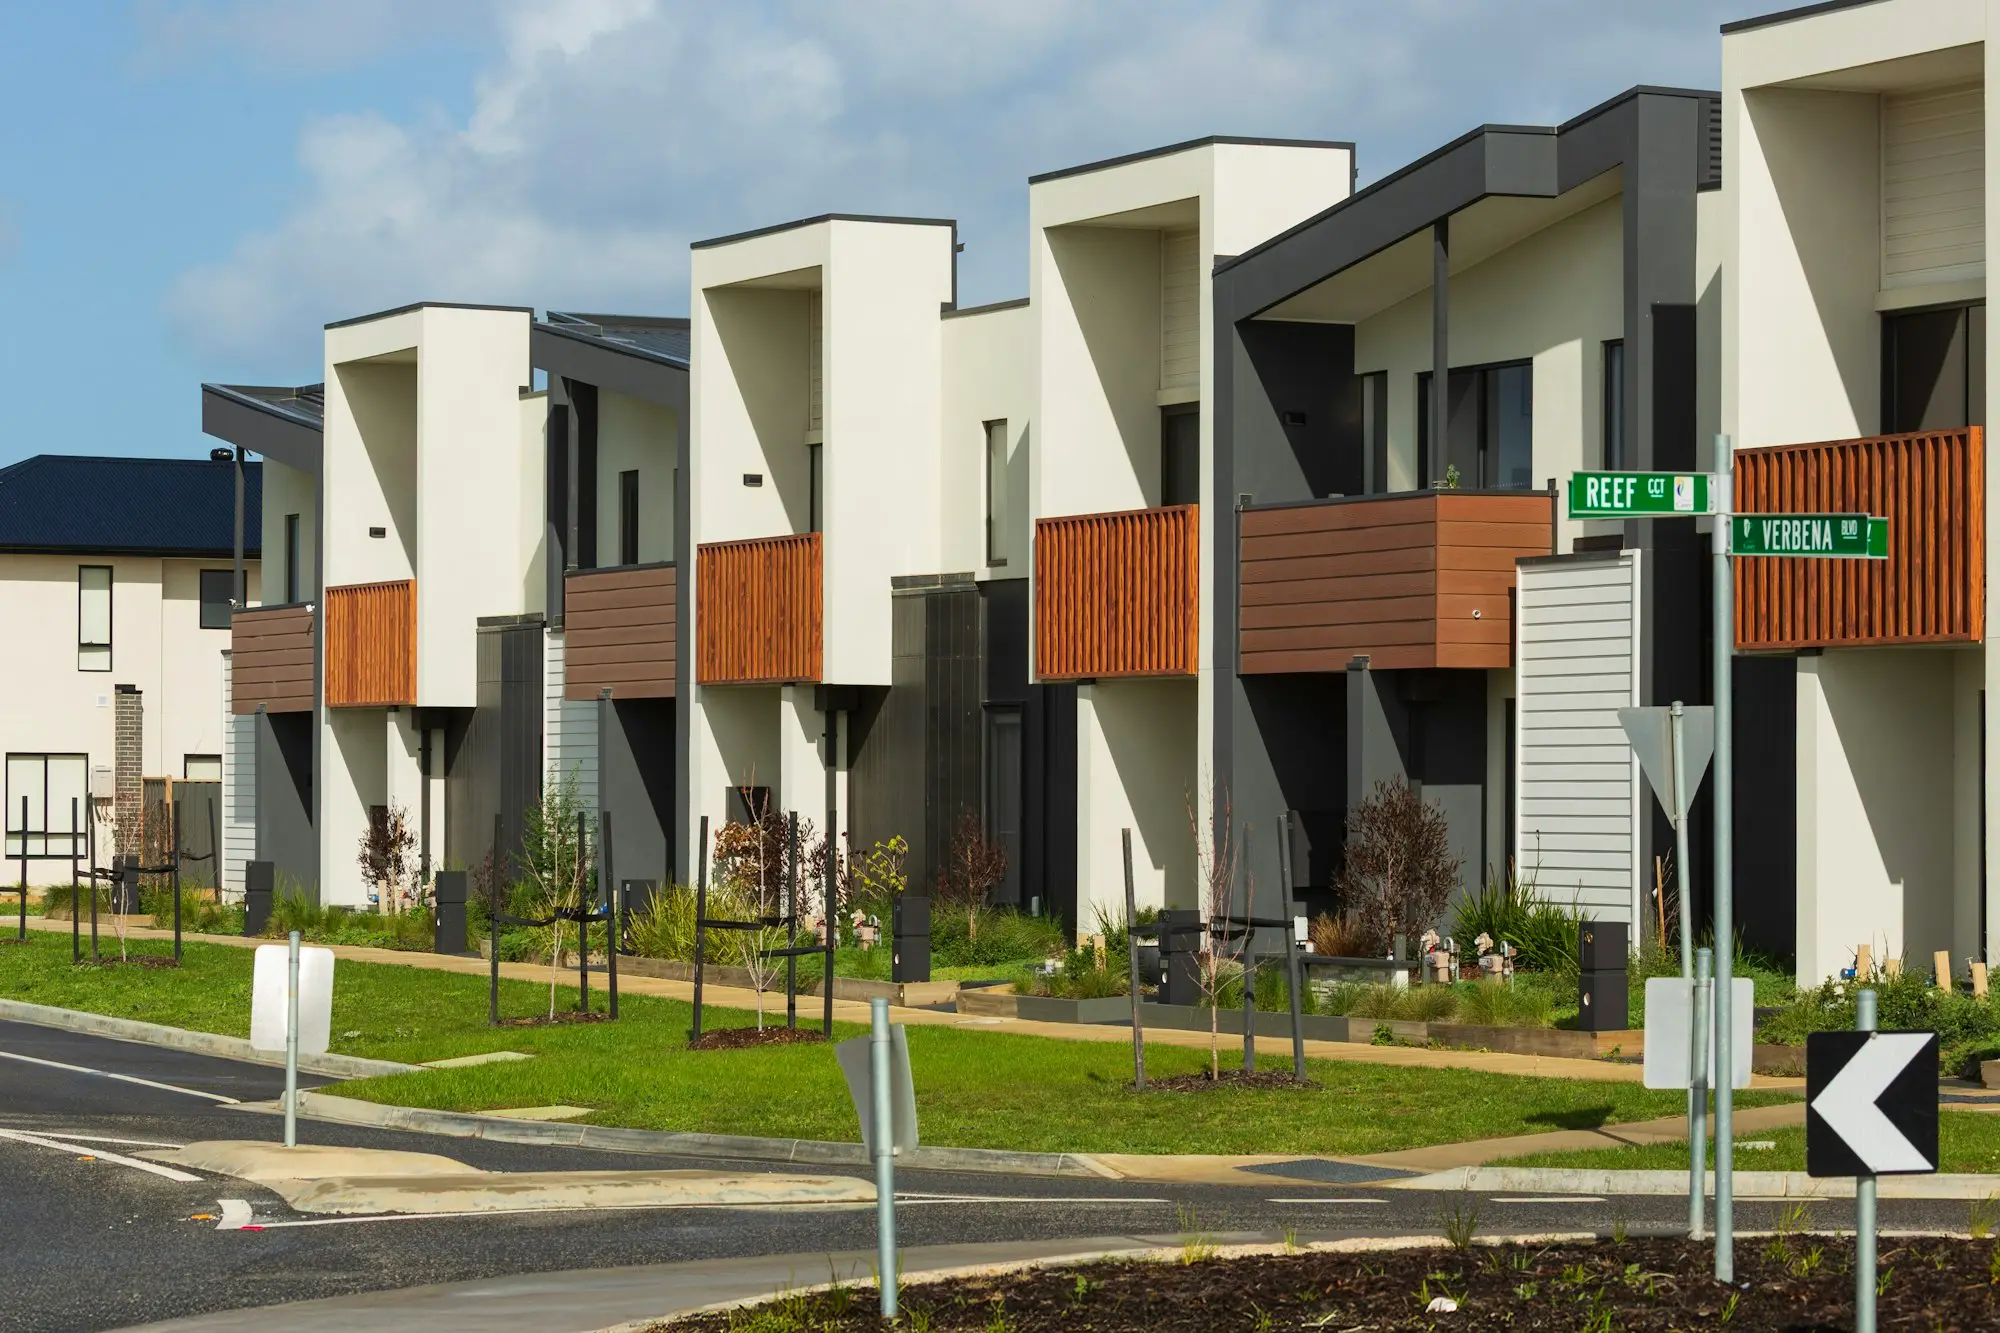
- unsold townhouses or terraces in a small subdivision
- display homes or spec homes a builder has finished but not yet sold
- a mix of stock across two or more completed projects
Why do developers end up needing one?
Construction facilities are written with a fixed term. They allow for the build plus a selling window, and a lot can shift inside that window: buyers’ finance falls over, the market softens, a neighbouring project floods the area with similar product, or a few pre-sales fail to settle.
When the facility expires with stock unsold, the developer usually has three options:
| Option | What it costs you |
|---|---|
| Discount the remaining units to sell them quickly | Margin, sometimes the whole project’s profit |
| Ask the construction lender to extend | Fees, tighter conditions, and no guarantee of a yes |
| Refinance the stock with a residual stock loan | A short-term loan, but you set the sale price and timing |
The third option is often the one that protects the most profit, provided the stock is genuinely saleable and the numbers leave room for holding costs.
How does repayment work as each unit sells?
The loan is structured with agreed release amounts for each title. When a unit sells, your conveyancer or solicitor arranges a partial discharge of the mortgage over that title, and the agreed amount comes out of the settlement proceeds to reduce the loan. The remaining titles stay as security for the balance.
Two tax points tend to affect the cash that actually arrives at each settlement, and both are worth raising with your accountant before you set release amounts:
- GST withheld at settlement. The ATO says that, where new residential premises or potential residential land is sold, most purchasers pay the withheld GST to the ATO at settlement and the balance to the seller. The seller must also give the buyer written notice before settlement. The money you see on settlement day is therefore less than the contract price.
- The margin scheme. Where it applies, GST is worked out on the margin rather than the full price, and the ATO notes that a buyer can’t claim a GST credit on a purchase made under the margin scheme. It is subject to eligibility and needs to be agreed in writing, so check before the contracts go out.
Ready to see what your remaining stock could support? Tell us about the units and what’s owing, and a specialist will come back to you.
Illustrative example: six units, two left
Illustrative: An Adelaide developer finishes a block of six two-bedroom units. Four settle on completion. The construction lender is still owed $820k, the facility expires in three weeks, and the two unsold units together are realistically worth around $1.3m.
- Loan: a private first mortgage of $860k over the two titles, covering the payout plus settlement costs
- Interest: capitalised, so no monthly repayments while the units are marketed
- Term: 12 months, giving the agent a full spring and summer selling season
- Release: an agreed release amount for each unit, so the first sale clears most of the loan and the second clears the rest
The developer avoids cutting the price on two units just to beat a bank deadline. Once both sell, the loan is gone.
What should you watch while you hold the stock?
Holding completed stock isn’t free, so build these into your exit plan:
- Land tax. In Victoria, the State Revenue Office assesses land tax on land owned at midnight on 31 December, based on the total site value of your taxable holdings, and all land is taxable unless an exemption applies. Stock carried across the new year may add to that year’s bill. Other states have their own rules, so ask your accountant how it applies to you.
- Renting the units. Tenants cover some holding costs, but the ATO treats residential rent as input taxed, and a property that has been rented for less than five years can still be new residential premises for GST. Leasing new stock can therefore change your GST position, so get advice before signing leases.
- Strata levies, insurance and agent marketing. Small individually, but they add up over twelve months.
Capitalising the interest helps, because the loan carries its own interest cost and your cash is free for these other items. Read more about how that works in prepaid or capitalised interest.
What does a lender look for in residual stock?
Without a formal valuation, the lender forms its own view of the stock, and it pays attention to:
- Saleability. Is the product right for the location? Are there recent comparable sales?
- Quantity versus market depth. Twenty identical units in a small town is a different proposition from three townhouses in a busy suburb.
- The selling plan. Who is the agent, what is the asking price, and what has buyer feedback been?
- The overall debt position. Including any GST and tax amounts that need to come out of settlements.
Credit history is considered case by case. A project that ran over time, or an ATO debt left over from the build, isn’t automatically a barrier when the stock itself is sound and the exit is realistic.
If the residual stock alone doesn’t quite cover the payout, another property can be added as extra security. The multiple properties as security page explains how that works, and the developer finance hub covers the wider picture.
Check whether your stock qualifies
Asking costs you nothing on the credit file: there is no credit check to enquire. Your enquiry isn’t broadcast to a list of lenders either. It goes to one direct lender, our lending partner fundU, and is read by a person who deals with developers.
Give us the real picture: how many titles, where they are, what each is likely to sell for, and the exact payout figure from the construction lender. That accuracy is what lets the specialist give you an answer you can rely on from the first call. Start your residual stock enquiry and take the deadline pressure off your sales campaign.
Frequently asked questions
What counts as residual stock?
Residual stock is the completed dwellings left unsold once a project has finished construction and the titles have issued. It might be the last three apartments in a block, a pair of townhouses or a handful of house-and-land lots. The key point for lending is that the stock is finished and individually titled.
Why would a construction lender want to be repaid before the units sell?
Construction facilities are written for a set term that covers the build and a selling period. If sales are slower than forecast, the facility can reach its expiry date with stock still unsold. A residual stock loan refinances that debt so the construction lender is paid out and you control the selling timetable.
Can I rent the units while I wait for buyers?
You can, but talk to your accountant first. The ATO treats residential rent as input taxed, and leasing new stock can change the GST position on its eventual sale. A property rented for less than five years can still count as new residential premises for GST purposes.
How is the loan repaid as units sell?
Each sale settles with a partial discharge of the mortgage over that title, and an agreed portion of the sale proceeds goes to reducing the loan. The release amounts are set out upfront so you and your conveyancer know exactly what is needed at each settlement.
Do you need a valuation of every unit?
No formal valuation is required. The lender assesses the stock itself, looking at the product, location and comparable sales, which avoids the cost and delay of commissioning reports on every title.